 Canada (EN)
Retirement readiness often gets framed as a math problem. Save a little more. Increase your contribution rate. Stay invested. Don't panic when markets are volatile. This is all good advice, but for many employees, the biggest obstacle to retirement readiness isn't a lack of financial knowledge. It's the reality that life keeps handing them bills.
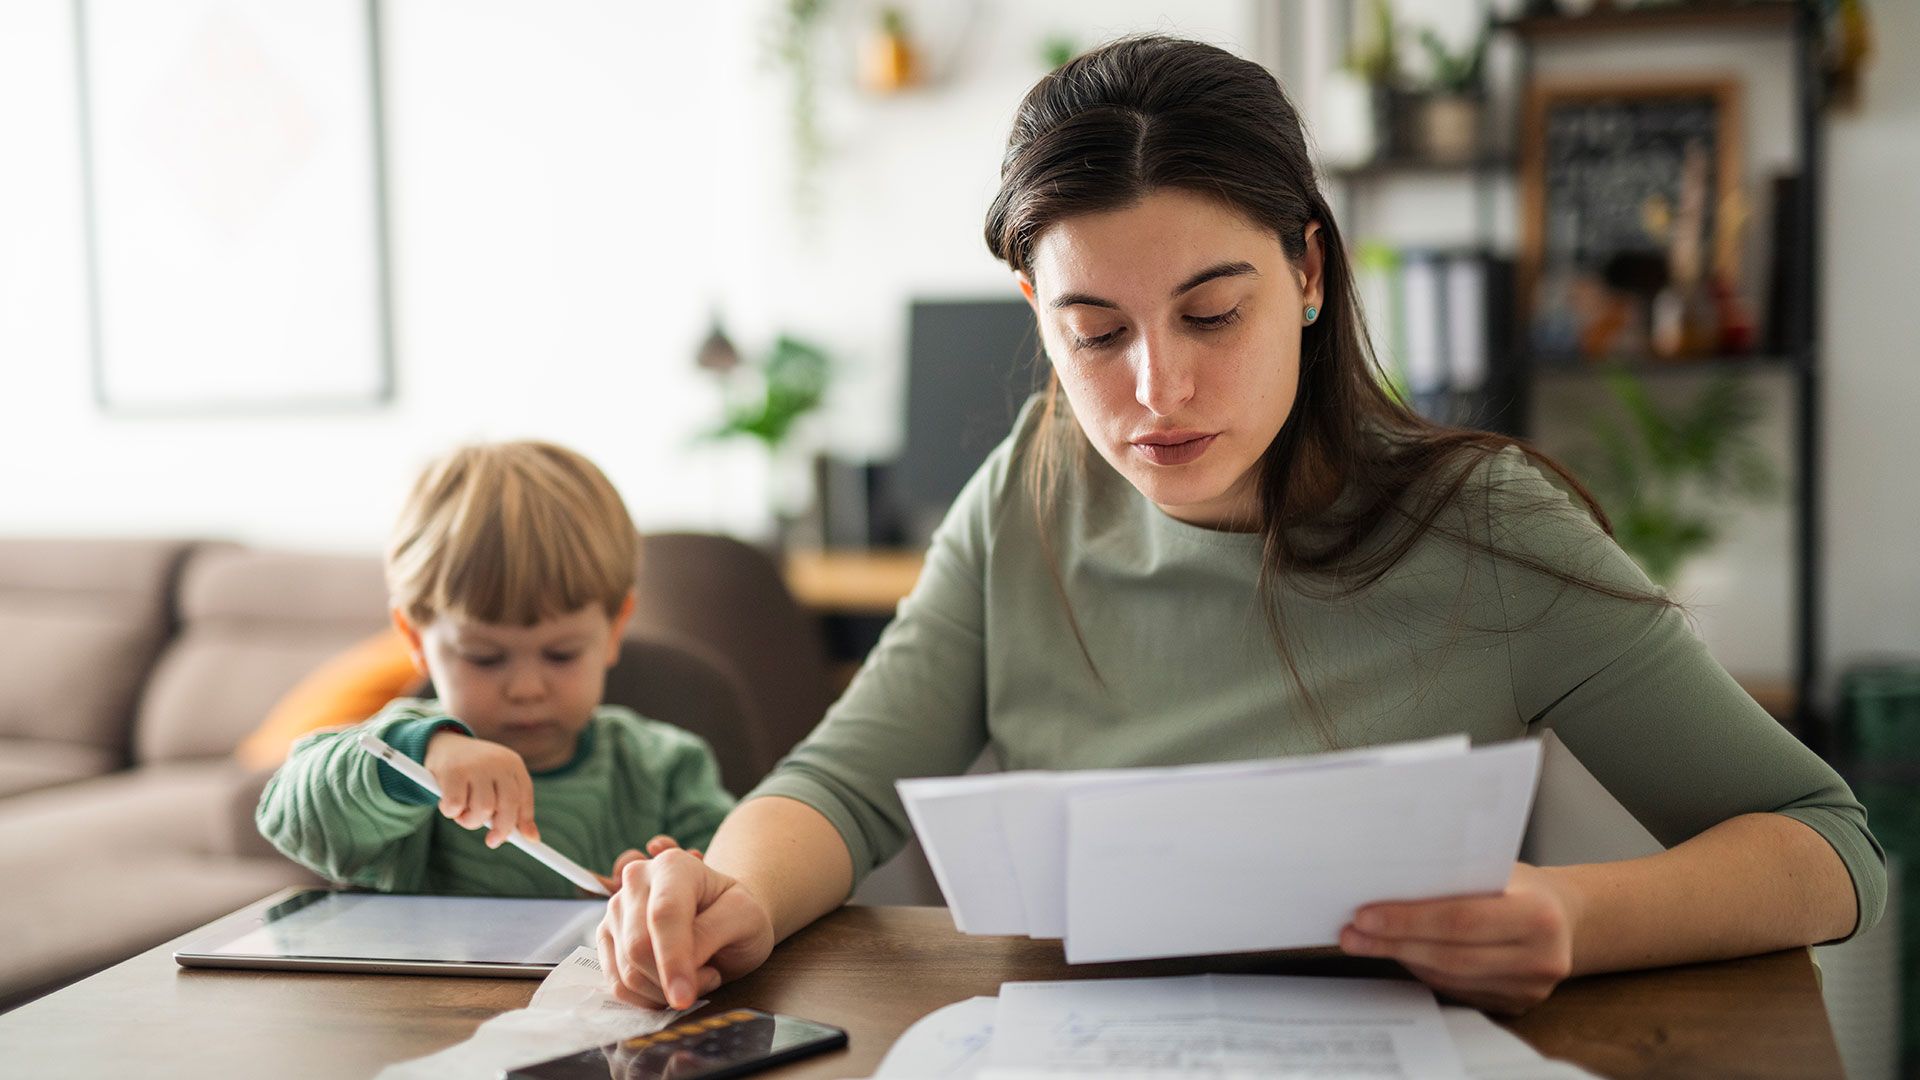
The washing machine breaks. A child needs braces. The car needs new tires. A medical bill appears unexpectedly in the mailbox. Suddenly, the money that was supposed to go toward retirement has a much more immediate assignment. It's hard to think about age 65 when you're worried about making it to the next payday.
The 2026 Alight U.S. Employee Mindset Study illustrates this challenge. Just 45% of employees rate their financial wellbeing highly. More than four in 10 say they're simply getting by financially, and nearly half identify personal finances as their biggest source of stress.
Competing priorities
Employees aren't necessarily choosing between spending and saving. Increasingly, they're choosing between competing necessities. Do I save for retirement or pay for childcare? Do I build an emergency fund or cover a healthcare expense? Do I increase my 401(k) contribution or absorb yet another increase in the cost of groceries, housing and everyday essentials?
These aren't hypothetical questions. They're real dilemmas facing real households every day.
Mindset data suggests many workers are operating without much financial margin for error. Only 27% of Americans have enough emergency savings to cover six months of expenses, while nearly one-quarter have no emergency savings at all. That helps explain why future-focused goals often lose out to present-day demands.
For years, retirement experts have talked about "leakage" from retirement accounts, but it often never gets there in the first place. Employees who are worried about paying this month's bills frequently can't prioritize saving for expenses that may be decades away.
The challenge becomes even more significant for workers approaching retirement. More than one-third of Mindset respondents don’t believe they’ll be able to retire when they want, with Gen X expressing particularly high levels of concern. That's consistent with broader industry research showing that retirement itself has become a source of anxiety.
The issue is bigger than retirement. It's about financial resilience. Someone with an emergency fund can weather a surprise expense without disrupting their long-term goals. Someone without that safety net may need to pause retirement contributions, accumulate debt or withdraw existing savings to solve an immediate problem.
That's why employers have an opportunity to rethink what financial wellbeing means.
Seeking stability
Historically, workplace financial programs have centered on retirement planning, investment education and increasing 401(k) participation. Those all remain incredibly important. However, employees are increasingly asking for support that acknowledges the financial realities they're facing today.
The most effective programs help workers make progress on both short-term and long-term goals simultaneously. This can include emergency savings programs, budgeting tools, debt management resources, student loan support, healthcare cost education and personalized financial guidance. Nearly half of employees in the Mindset Study say they would like their employer’s help establishing an emergency savings fund, a clear signal that workers are looking for assistance building a stronger financial foundation before they can fully focus on the future.
Asking employees to prioritize retirement savings without addressing their immediate financial pressures is a bit like telling someone to plan a cross-country road trip when they're worried about whether they'll have enough gas to get home tonight.
Retirement readiness doesn't start with retirement. It starts with financial stability. Employees who feel confident managing today's financial challenges are more likely to contribute consistently, stay invested through market volatility and remain focused on long-term goals. They are more resilient. Less stressed. More engaged.
The conversation about financial wellbeing should not be limited to helping employees retire someday. It should also focus on helping them navigate the realities of today—because when employees feel more secure about next month's bills, they're far more likely to believe in next decade's retirement.


